High-Yield Savings Accounts: A Worldwide Comparison Checklist
High-Yield Savings Accounts: A Worldwide Comparison Checklist A practical, worldwide guide built around total cost, trade-offs and a real-life decision.
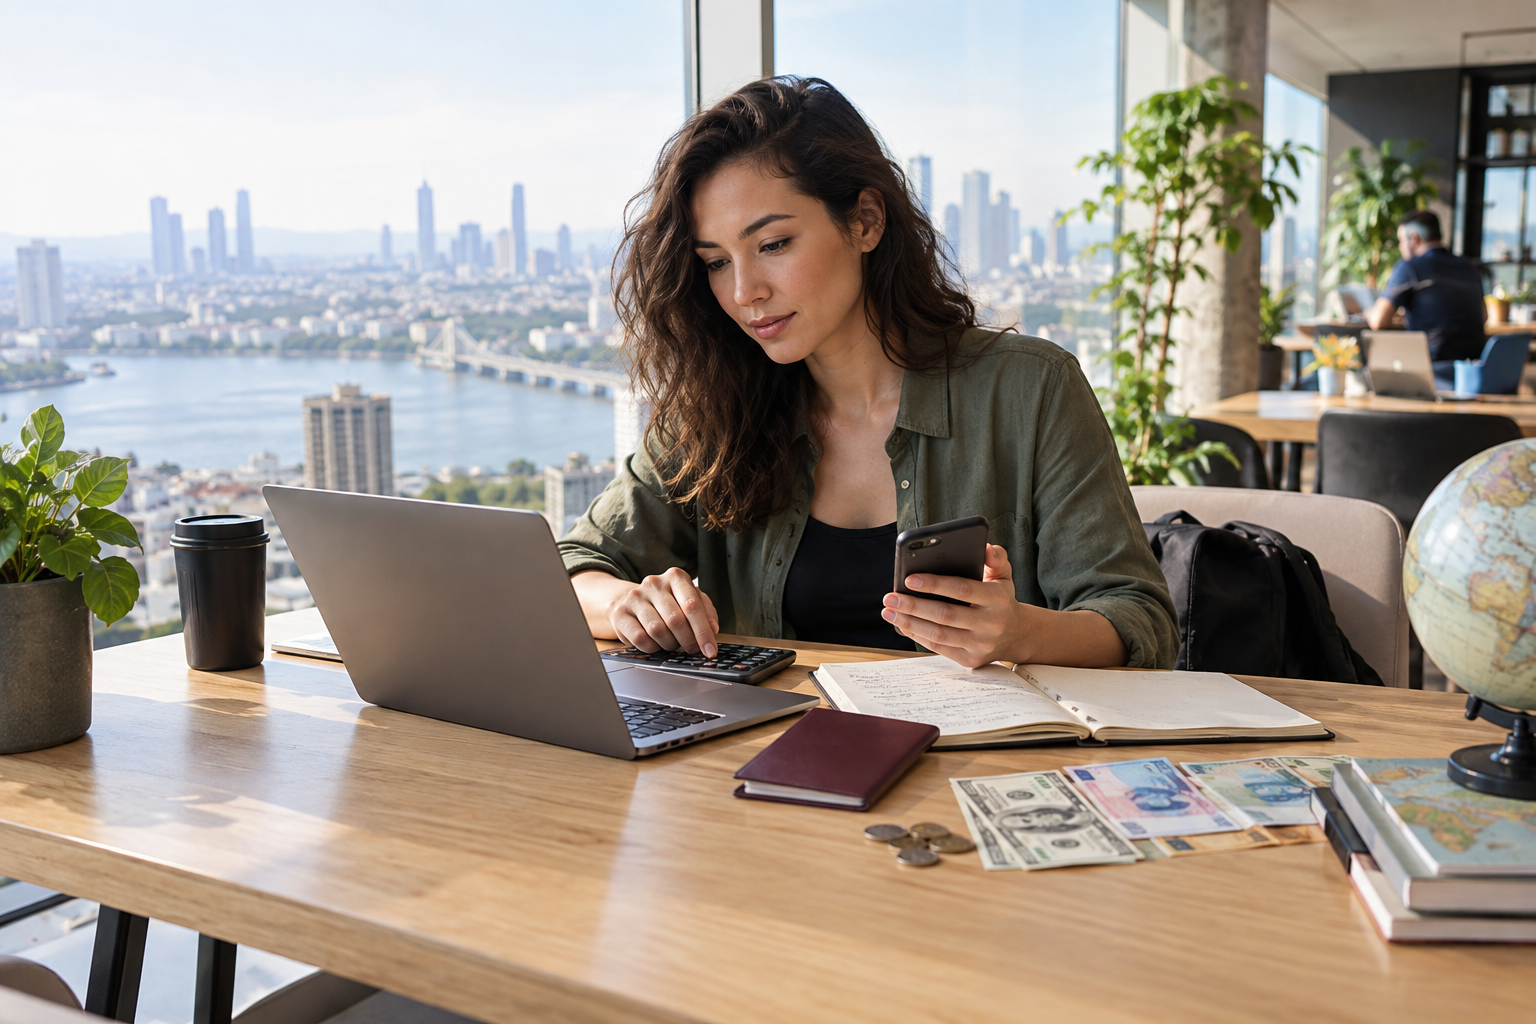
Mei has built a cash buffer and wants interest without locking away money she may need for a visa renewal. This is the kind of decision that looks simple in an advertisement and becomes more complicated once fees, timing and everyday behavior enter the picture.
The short answer
Emergency savings should prioritize safety and access before yield. The right product is the one that remains affordable in a normal month and understandable in a stressful one. Availability, consumer protection and tax treatment vary by country, so use this guide as a comparison framework and confirm local terms before applying or buying.
A real-life decision, not a headline number
Mei has built a cash buffer and wants interest without locking away money she may need for a visa renewal. Start by describing the job the product needs to do. Separate essential requirements from attractive extras. That prevents a bonus, introductory rate or polished app from pulling attention away from the cost and protection that matter after the promotion ends.
Next, model two versions of the next year: a normal version and an inconvenient version. In the second, assume income arrives late, an urgent bill appears or plans change. A suitable choice should not require perfect behavior or perfect timing to remain manageable.
What to compare before you apply or buy
- Deposit protection in the bank’s jurisdiction. Write down the exact figure or rule for every option, then compare on the same time horizon.
- Withdrawal speed, rate conditions and balance tiers. Write down the exact figure or rule for every option, then compare on the same time horizon.
- Currency risk if savings and expenses differ. Write down the exact figure or rule for every option, then compare on the same time horizon.
Use a simple side-by-side table and keep the same assumptions for every provider. If one quote excludes a fee or uses a different term, add it back before deciding. Screenshots and dated copies of key terms can also help if an offer changes.
Buying advice for this situation
- Set a ceiling. Decide the maximum total cost, monthly commitment or deductible your budget can absorb before viewing offers.
- Shortlist three credible options. Include at least one simple, lower-cost alternative so premium features must prove their value.
- Read the unexciting pages. Pricing schedules, exclusions, renewal rules and complaint procedures often matter more than the headline.
- Verify the provider. Check the relevant regulator, licensing register or deposit/insurance protection scheme in your country.
- Sleep on the decision. Urgency is useful to sellers. Unless there is a genuine emergency, a pause improves comparison quality.
Common traps
- Promotional rates can fall after a short period.
- High headline yield does not compensate for weak access or currency mismatch.
- Do not rely on a monthly figure without calculating the total commitment.
- Do not submit several full applications merely to discover basic terms; ask whether a quote or eligibility check affects your credit record.
How affiliate links should fit the decision
A comparison link can save time, but it should be the start of verification, not the end. Check the provider’s current terms, confirm it operates in your country and compare at least one option that is not commercially featured. Financial Diet Blog does not accept payment for a favorable conclusion and will label compensated links clearly when they are added.
Questions readers ask
Is the cheapest option always best?
No. Price matters, but access, exclusions, flexibility, protection and support can justify a higher cost. Compare the total package against the job you need it to do.
How many providers should I compare?
Three is a useful practical minimum for many purchases. Add more when the commitment is large, long or difficult to reverse.
Can I use this guide in any country?
The framework is designed for worldwide readers, but laws, product names, taxes and protections differ. Confirm local rules with your regulator or a qualified adviser.
Primary sources and further reading
- CFPB financial service provider comparison — last checked 2026-09-27
- Investor.gov introduction to saving and investing — last checked 2026-09-27